Federal tax authorities are finally preparing to resolve the cannabis industry’s longest-running financial headache: Internal Revenue Code Section 280E. The Department of the Treasury and the IRS officially placed 280E guidance on their 2026–2027 Priority Guidance Plan, responding to the complex fallout of the federal government’s move to shift medical marijuana into Schedule III.
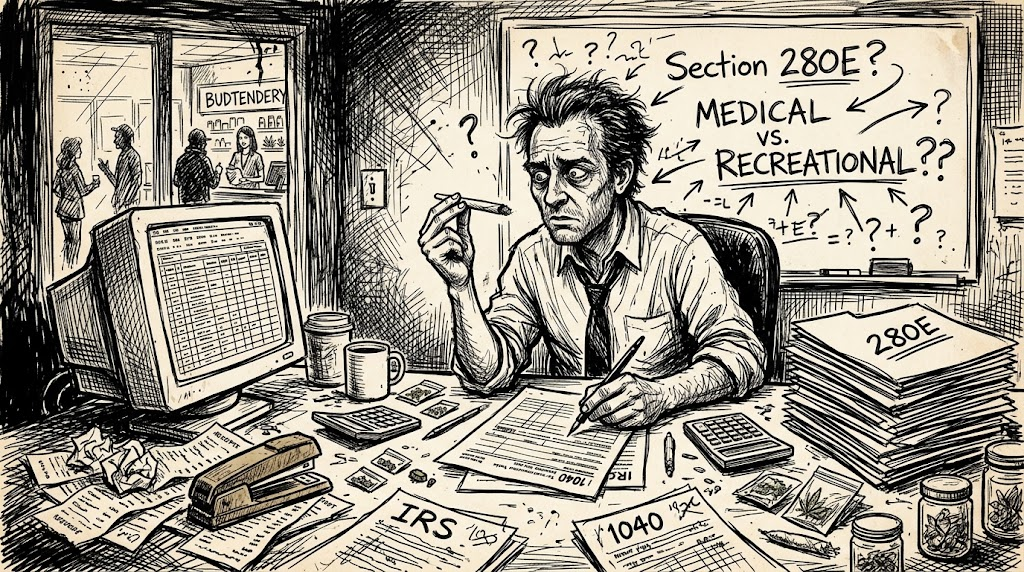
For decades, Section 280E has barred cannabis operations from taking standard business deductions and tax credits because the penalty explicitly targets entities trafficking in Schedule I and II substances. Rescheduling medical cannabis frees licensed operators from that restriction in theory, but reality remains murky because recreational marijuana is currently locked in Schedule I. This creates an accounting nightmare for hybrid dispensaries that cater to both markets, leaving operators uncertain how to legally apportion payroll, rent, and overhead between deductible medical sales and penalized adult-use shelves.
While Congressional leaders push Treasury for immediate clarity and opponents attempt to preserve the ban through legislation, the IRS’s new priority status signals formal rules are on the horizon. The forthcoming framework is expected to outline expense allocation strategies and determine whether businesses can claim retrospective tax relief, finally clarifying whether cannabis operators can write off their daily grind like any other legitimate business.
Dabbin-Dad Newsroom